Healthcare is one of the most complex systems consumers navigate. Members receive bills, claims, Explanation of Benefits (EOBs), provider notices, and coverage information that often require significant effort to interpret. While EOBs are designed to explain how plans cover care and what portion members owe, they frequently expose the complexity of the healthcare system rather than answering the questions members have in the moment.
For example: If I ask what time it is, a detailed explanation of how clocks work does not answer my question.
The distinction matters because members experience healthcare complexity as a moment of uncertainty, rather than an abstract system problem.
Is this visit covered? What will this cost? What should I do next?
Health plans build trust when they answer those moment-specific questions clearly, rather than asking members to sort through every rule, exception, and dependency behind the answer. Members are not asking plans to expose the clockworks. They are asking for the information that matters right now.
Healthcare is complicated; if there were simple explanations, we would give them. In the absence of simplicity, we often turn to transparency: let me show you why this is hard to understand. But transparency and simplicity do not need to be mutually exclusive.
Building both in healthcare requires two things: personalization and trust.
Personalization eliminates a layer of complexity by curating what applies to a specific member. The system may remain complex, but the member no longer has to determine which parts of that complexity matter to them.
Every touchpoint is an opportunity to shift the burden of understanding and build incremental trust. Engagys helps health plans find those opportunities across individual communications and end-to-end journeys. And while full experience transformation matters, plans can begin quickly with touchpoints they already own.
Personalization Solves Complexity
The difference becomes clearest when we compare a generic transparent message with a personalized one. For example, a member gets a message at the start of the plan year:
[Generic message]
Your health insurance plan has the same name as it did last year, but your network has changed. Some of your providers are now out-of-network, which means you can still see them, but it might cost you more. How much more depends on whether you’ve met your deductible — your out-of-network deductible, which is different from your in-network deductible — and your plan’s coinsurance rate.
The message is not inaccurate, but each uncertainty — “some,” “might,” “depends” — pushes interpretation back onto the member. This uncertainty may leave members thinking, “If my health plan doesn’t know which of my providers are in-network, then how am I supposed to know?”
Over time, that uncertainty erodes trust and increases the cost of understanding. Personalized communications can project reliability, reduce cognitive burden, and position the plan as a partner rather than an obstacle in care.
Now imagine the same moment handled differently, with personalized information delivered in the member’s preferred channel:
[Personalized message]
Dr. Goldberg is out-of-network this year, so you’ll pay more if you see Dr. Goldberg instead of an in-network provider. Here’s how that works, based on your most recent visit:
| In-network | Out of network | |
| Negotiated visit cost | $350 | |
| Your plan pays | 80% -> $280 | 60% -> $210 |
| You pay | 20% -> $70 | 40% -> $140 |
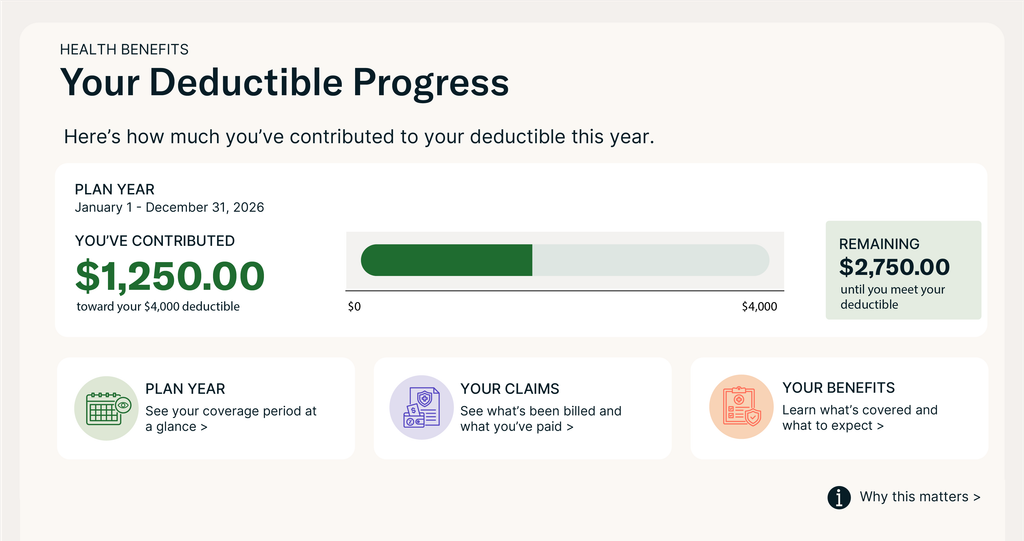
You have a couple of options:
- See Dr. Goldberg and pay the higher out-of-network rate for your care.
- Choose an in-network provider and pay less for your care.
In-Network Providers
| Philip Anders, NP | Dr. Sheila Yu | Dr. Francis Edwards |
| 2.1 miles from you | 4.1 miles from you | 6.4 miles from you |
| Offers online scheduling | Offers telehealth and online scheduling | Offers telehealth |
| Book an appointment | Book an in-person appointment Book a telehealth appointment | Call to book an appointment |
In this version, the plan applies the rule to the member’s actual situation, shows the financial implication, and offers a next step. The member can make an informed decision with less friction and cognitive burden. Healthcare remains just as complicated, but the moment becomes simpler.
Starting with Impact: Explanation of Benefits (EOBs)
Explanations of Benefits (EOBs) are a practical starting point on the path to personalization because they are a communications tool that sits at the intersection of claims, costs, benefits education, and member trust. They are frequent, familiar touchpoints, but for many members they raise as many questions as they answer. A document intended to help members understand their insurance and claims can instead deepen uncertainty and mistrust.
Health plans have the opportunity to treat the EOB not as a mandated box-checking exercise, but as a recurring opportunity to simplify through personalization, strengthen benefits education and financial literacy, and differentiate as a partner in health. In an AI-powered present and future, the case for dynamic, hyper-personalized EOBs becomes even stronger: the more precisely plans can understand context, the more responsibly they can help members act on it.
When EOBs use plain language, simple visuals, and personalized financial information connected to supported action, they do more than explain a claim. They reinforce the member’s confidence in their own understanding and in their plan as a trustworthy partner.
Upstream Impact: Advanced Explanations of Benefits (AEOBs)
If EOBs show how plans can build trust after a member receives care, AEOBs extend that responsibility upstream, when member comprehension can still influence decision-making.
AEOBs are part of the evolving mandates under the No Surprises Act, and they create an opportunity for health plans to extend trust-building — or trust-breaking — earlier in the member journey. Part pre-service Good Faith Estimate, part coverage check, the purpose of AEOBs is to combine provider billing details and health plan benefits to give members a view of their costs before care, while they still have time to ask questions, compare options, and make informed decisions.
While practical and logistical requirements are still in flux, health plans should consider how this upstream touchpoint will contribute to transparency and trust. Engagys helps clients implement adaptable AEOB experiences that align with forthcoming mandates and draw on best practices from other regulated industries with similar pre-service cost estimate requirements.
It’s Time to Turn Complexity into Confidence
The same principle applies beyond EOBs and AEOBs. Members judge trustworthiness not by the volume of information offered, but by whether that information feels accurate, relevant, accessible, and safe to act on. In member experience, transparency often comes from curation: extracting the information that matters, simplifying it, and delivering it in the moment when a member needs it.
Personalization is the key to that kind of simplification, starting in touchpoints health plans already own and extending into future-state moments like AEOBs and AI-enabled guidance. Ideally, those moments become part of a holistic n=1 member experience that adapts to each person’s needs, preferences, accessibility requirements, and context over time.
In healthcare member experience, indiscriminate transparency can become another burden for members to carry.
Engagys can help your organization identify the most valuable information for a specific member in a specific moment, then turn that information into experiences that are clear, timely, and actionable.
You already have the clock built and running smoothly. We’ll help you tell members the time.
Watch the Full Interview Here
Frequently Asked Questions
1. Why are Explanation of Benefits (EOBs) so difficult for members to understand?
While EOBs are supposed to make claims processing and financial responsibility easier to understand, they are part of the same complex system they’re designed to explain. Complicated concepts like deductibles and cost-sharing get even murkier with uncertain language about what a member “may owe” or what a plan “may cover.” It’s like trying to read a scientific paper as a non-scientist.
2. How can personalization make healthcare communications easier to understand?
Personalization filters out everything that’s not relevant and removes uncertainty. Instead of “some of your medications may be covered at X% after your deductible,” we get “Your Metformin refill next month will cost $15. Here’s how we got to that number.” The information is all relevant, accurate, and actionable.
3. What is the difference between transparency and personalization in member communications?
It’s like using a map versus a GPS. A map transparently shows you all possible routes to your destination so you can weigh the positives and negatives and decide for yourself; a GPS shows you a personalized route within those options. Transparency gives you the whole map; personalization helps you choose the right route, based on what matters to you in that moment.
4. Why are EOBs an important opportunity for health plans to build trust?
Often EOBs “check the box” of regulatory requirements, but they are positioned to be so much more. With n=1 personalization, EOBs document plans’ fulfilled commitments; they surface members’ most valuable unused benefits; they reinforce the plan’s transparency and reliability without overwhelming members with superfluous detail. Evolving expectations about digital and AI-powered healthcare experiences only strengthen the position of EOBs as key member communications.
5. What are Advanced Explanations of Benefits (AEOBs), and how do they help members?
AEOBs add pre-service estimates into the mix, so members have a fuller picture of costs before they receive care. Providers and plans connect to create pre-service cost and coverage estimates that help members understand and plan for costs before the bill arrives. AEOBs are part of the No Surprises Act, and while they’re not mandated yet, many plans and providers are already thinking about how to implement them.
From a member experience perspective, AEOBs can build (or break) trust even earlier in the care journey. Like pre-service estimates in other regulated industries, members will likely look to AEOBs as decision support tools; as such, they’re great opportunities for in-network steerage and benefits education while members have time to explore their options.
6. How can health plans reduce member confusion without oversimplifying healthcare?
Personalization and answering the right questions at the right moment. Is this covered? What will it cost? What do I do next? Combining deep personalization with clear, plain language, intuitive visuals, and actionable recommendations, plans can simplify the experience of healthcare while maintaining transparency on the complex healthcare process.